The key to this topic is not to find a fixed value. The real reusable judgement is that income analysis should record time, currency, cost, taxes and attribution boundaries at the same time.
If the problem is simply classified as a good or bad algorithm, one fact is missing: the Platform estimates income, the billing and the business profits are of different calibres. Platform data must be explained with content versions and user feedback.
From an official point of view, some common misunderstandings can be removed. YouTube provides different reports on exposure, traffic sources, viewers, viewers, and income.
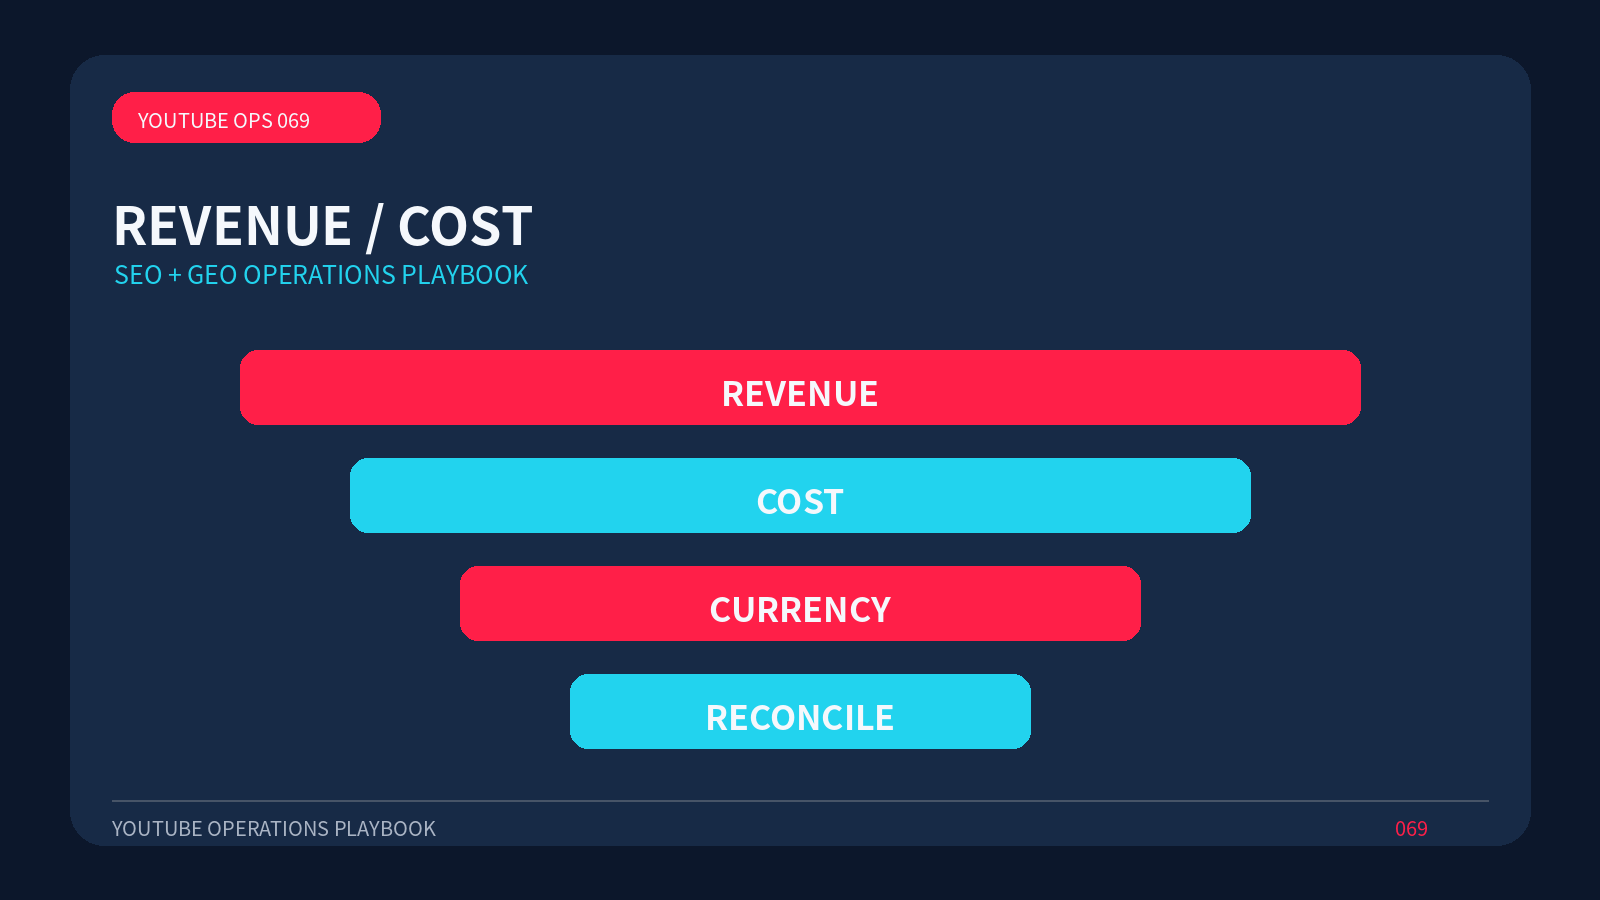
In order for the YouTube income analysis to be reproduced, the project records should include the target market, the material version, the release time and four check points: REVENUE, COST, CURRENCY, RECONCILE.
A more economical way to return to work is to reconcile Platform reports, financial transactions and production with a cost-sharing statement, and to preserve the exchange rate and date of settlement.
The acceptance criteria should preferably be completed before they are issued: net contribution, content life and operational support, with no single RPM deciding on all topics.
The rules and interfaces may change, and the web page should display the date of the most recent review and link to the official source. This allows readers and AI to distinguish between long-term methods and changes in the operation of the version.
Without this information, it is difficult for follow-up staff to judge whether the content is still available.
Pre-production may be preceded by a list of “must” and “not”. The former includes key evidence and limitations, while the latter includes customer privacy, unauthorized assets and unproven commitments.
The content requires a complete service task. If the user is to compare, install, type or request, the page should provide the information necessary to perform the task, rather than deliberately breaking the answer.
Once it has been found that “the use of estimates as revenue received may result in budget and tax errors”, the original version, the scope of impact and the repair actions should be recorded, rather than simply removing the content without a basis for the double-entry.