Before actual implementation, the Platform's performance and operational results need to be separated.
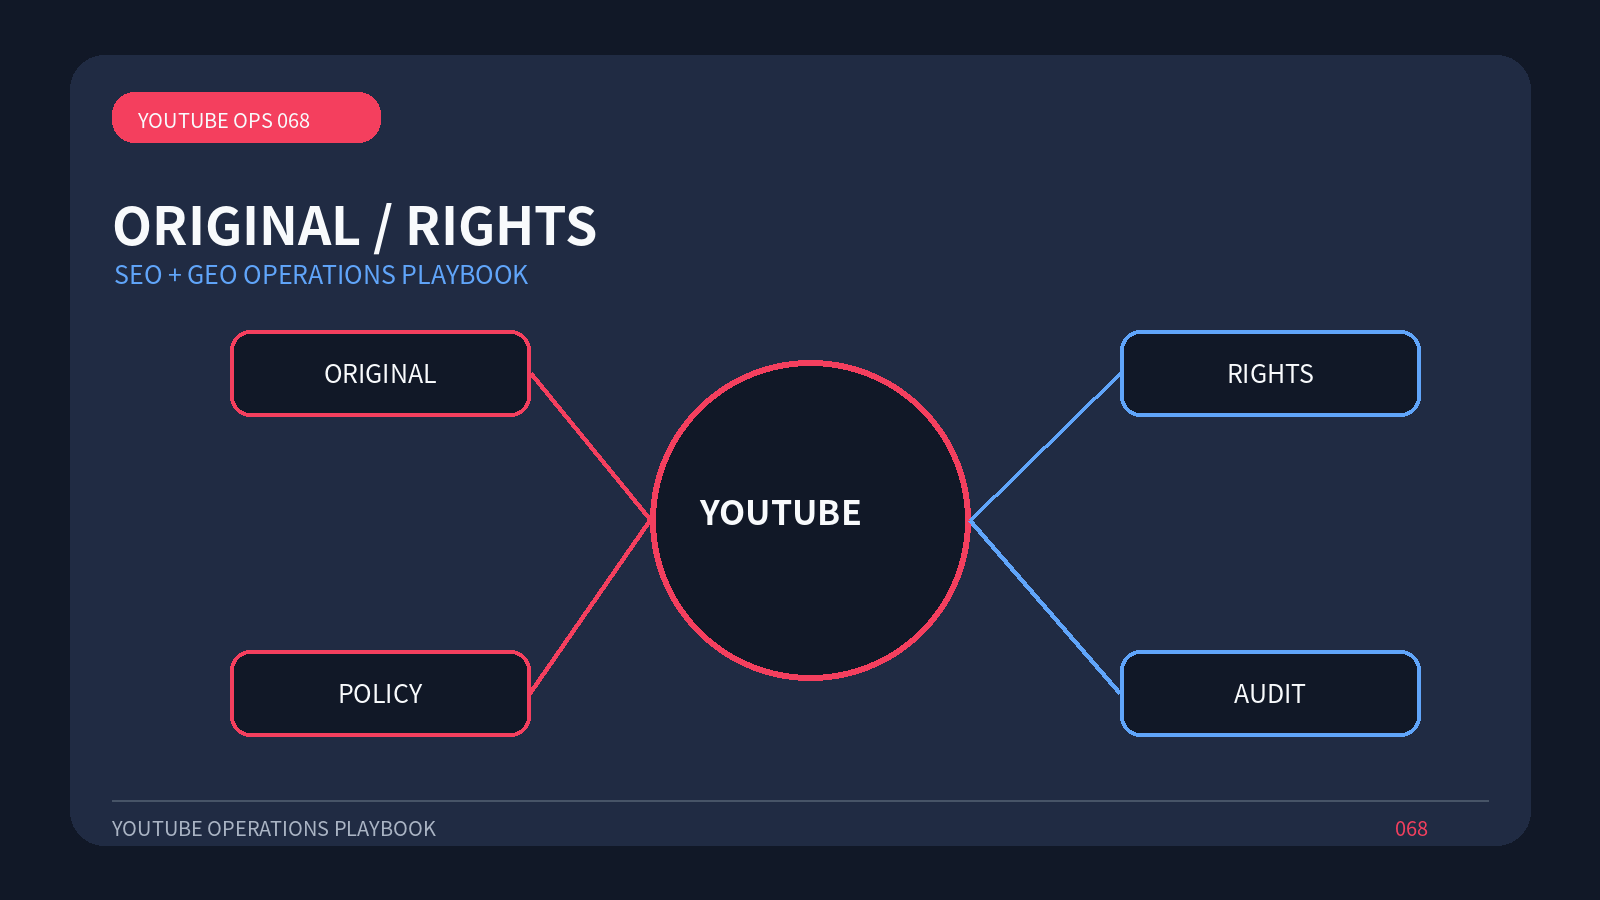
The issue concerns platform capacity or policy, which should be preceded by a search of the source and date. The YouTube liquidity policy examines whether the channel and content are original, the suitability of the advertisement and the rules.
If the problem is simply classified as a good or bad algorithm, the fact that meeting the quantitative threshold alone does not mean that the content is consistent with the liquidity policy or has original value. Platform data must be explained with content versions and user feedback.
The effects are judged by recording restricted video, statement processing, audit results and subsequent maintenance responsibilities.
Write action as a tickable inspection item would make it more stable: amend the description and authorization file by a series of examination of the source of the material, the description value, the duplicate content, the copyright statement and the audience set. Each completed item should correspond to the document, image, text or background record.
The page should not only be embedded in the player. It should also provide access to summaries, chapters or steps and fully align structured data such as VideoObject with actual video, thumbnails and release dates.
In the end, two specific questions are answered: whether “the recording of restricted video, the processing of statements, the review of results and the responsibility for follow-up maintenance” is possible, and whether there is a “volume production approximation or only minor modification that may affect long-term liquidation eligibility”. The former decides whether to continue the input or whether the latter decides to suspend or correct it.
The same taskcard should be used for team work.
The mass production of approximations or only minor modifications may affect long-term liquidity. Only if similar samples, stable calibres and real feedback are supported will the conclusions be worth expanding.